
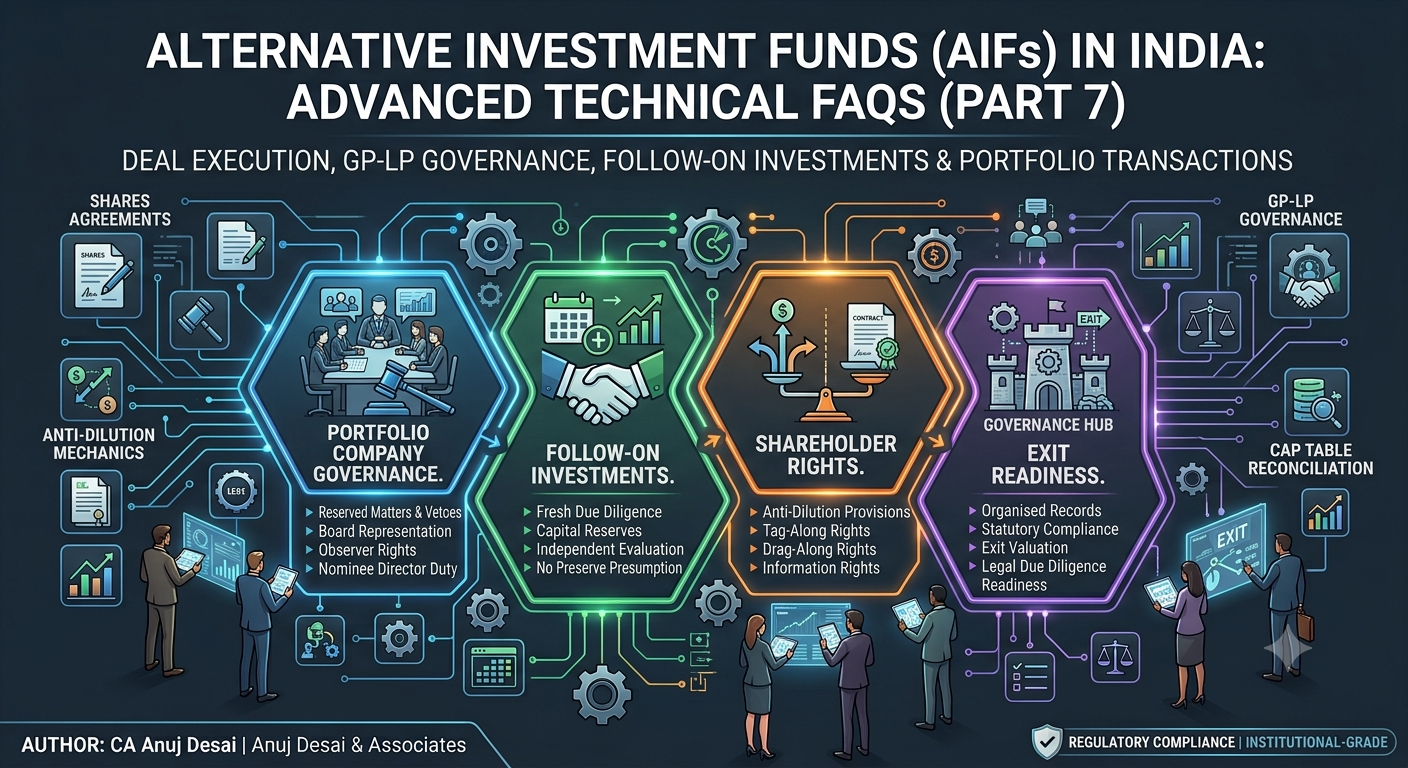
Portfolio Company Governance
Why should an Alternative Investment Fund negotiate board representation before making an investment?
Board representation provides the fund with visibility into strategic decisions, financial performance, governance practices and operational risks. It also enables the fund to participate in decisions relating to capital raising, acquisitions, business restructuring and corporate governance without interfering in day-to-day management.
What are Reserved Matters in portfolio company investments?
Reserved Matters are predefined corporate actions that cannot be undertaken by the portfolio company without obtaining prior approval from specified investors, directors or shareholders. These typically include amendments to constitutional documents, issuance of securities, borrowings above agreed thresholds, mergers, liquidation, disposal of substantial assets and related party transactions.
Why should Reserved Matters be proportionate to the size of the investment?
Overly extensive veto rights may impede business operations, discourage future investors and create governance deadlocks. Reserved Matters should therefore be calibrated to protect legitimate investor interests without impairing commercial flexibility.
What is a Board Observer right?
A Board Observer is an individual nominated by an investor who is entitled to attend board meetings, receive board materials and observe deliberations without possessing voting rights. Observer rights are commonly negotiated where formal board representation is commercially impractical.
Should an Alternative Investment Fund maintain governance protocols for its nominee directors?
Yes. Nominee directors should understand their statutory duties, confidentiality obligations, conflict management responsibilities and reporting expectations. Formal governance protocols reduce legal uncertainty and improve consistency across portfolio companies.
Follow-on Investments
What is a follow-on investment?
A follow-on investment is an additional capital infusion made by an Alternative Investment Fund into an existing portfolio company after the initial investment has already been completed.
Why are follow-on investment reserves important during fund planning?
Many successful investments require multiple funding rounds before reaching profitability or an exit event. Maintaining sufficient capital reserves enables the fund to protect its ownership percentage and continue supporting high-performing portfolio companies.
Should every follow-on investment undergo fresh due diligence?
Yes. Although the fund is already invested, follow-on rounds should be supported by updated financial analysis, legal review, business performance assessment, valuation review and investment committee approval before additional capital is deployed.
Can an Alternative Investment Fund decline to participate in a follow-on round?
Yes. The Investment Manager may decide not to participate where the portfolio company's prospects have deteriorated, valuation is commercially unattractive or participation would conflict with the fund's investment strategy or diversification objectives.
Should follow-on investment decisions be evaluated independently from the original investment?
Absolutely. Previous investments should never create an automatic presumption in favour of additional funding. Every follow-on investment should be evaluated based on current commercial merit rather than historical commitment.
Shareholder Rights
What is an anti-dilution provision?
An anti-dilution provision protects an investor against dilution resulting from subsequent issuances of shares at lower valuations by adjusting the investor's conversion ratio or economic entitlement in accordance with the agreed contractual mechanism.
What is a Tag-Along right?
A Tag-Along right enables minority investors to participate proportionately in the sale of shares by a controlling shareholder, ensuring that minority investors receive an opportunity to exit on substantially similar commercial terms.
What is a Drag-Along right?
A Drag-Along right permits specified majority investors to require minority shareholders to participate in a sale transaction, thereby facilitating the transfer of complete ownership to an acquirer without minority holdout risk.
Why are Information Rights important for Alternative Investment Funds?
Information Rights provide periodic access to financial statements, budgets, management reports, operational updates and other material information required for investment monitoring and governance.
What is a Right of First Refusal (ROFR)?
A Right of First Refusal grants existing investors the opportunity to purchase shares proposed to be transferred by another shareholder before those shares may be offered to external purchasers.
Dilution & Capital Structure
Why should Alternative Investment Funds continuously monitor ownership dilution?
Ownership percentages may change due to employee stock option plans, convertible instruments, additional funding rounds or corporate restructurings. Continuous monitoring enables accurate valuation and governance planning.
How can employee stock option plans affect institutional investors?
Large employee stock option pools may reduce the percentage ownership of existing investors. Consequently, dilution assumptions should be incorporated into investment models before the transaction is completed.
Should conversion mechanics of convertible securities be independently verified?
Yes. Conversion ratios, conversion events, adjustment clauses and dilution provisions should be carefully reviewed because relatively small drafting errors may significantly affect investor economics.
Why should cap tables be periodically reconciled?
Cap table inaccuracies may result in ownership disputes, valuation errors, incorrect investor reporting and difficulties during future fundraising or exit transactions.
Should Alternative Investment Funds maintain independent cap table records?
Yes. Independent cap table verification strengthens governance and reduces reliance solely upon records maintained by portfolio companies.
Exit Readiness
Why should exit planning begin immediately after making an investment?
Institutional investors often evaluate exit pathways before deploying capital. Early planning improves strategic alignment, corporate governance, documentation standards and value creation initiatives throughout the investment lifecycle.
What operational improvements increase exit readiness?
Strengthening financial reporting, statutory compliance, governance practices, management information systems, internal controls and documentation enhances attractiveness to strategic buyers and financial investors.
Why should legal due diligence readiness be maintained continuously?
Maintaining organised legal records throughout the investment period significantly reduces transaction timelines and execution risk during eventual exits.
Can poor governance reduce exit valuation?
Yes. Governance deficiencies frequently increase perceived investment risk, resulting in valuation discounts, extended negotiations or failed transactions.
Why should Alternative Investment Funds periodically perform exit preparedness reviews?
Regular exit readiness assessments enable Investment Managers to identify documentation gaps, governance weaknesses, unresolved litigation, regulatory issues and operational deficiencies before initiating sale processes.
Need Expert Assistance with Alternative Investment Funds?
Whether you require assistance with portfolio governance, shareholders' agreements, investment documentation, follow-on investment structuring, cap table reviews, investment committee governance, PPM drafting, PPM Audit, SEBI compliance, fund accounting or institutional fund governance, Anuj Desai & Associates provides specialised advisory services across every stage of the Alternative Investment Fund lifecycle. Our professionals advise Sponsors, Investment Managers, Trustees, Venture Capital Funds, Private Equity Funds, Family Offices, Infrastructure Funds and institutional investors on transaction structuring, governance, regulatory compliance and investment execution. Connect with Anuj Desai & Associates to establish institutional governance standards and maximise long-term value creation across your Alternative Investment Fund portfolio.
Disclaimer
This article is intended solely for general informational and educational purposes and should not be construed as legal, regulatory, tax, accounting or investment advice. Certain governance concepts discussed above arise from commercial practice, negotiated investment documentation and institutional market standards in addition to statutory requirements. The applicability of these concepts depends upon the governing agreements, the SEBI (Alternative Investment Funds) Regulations, 2012, applicable circulars and the specific facts of each transaction. Readers should seek independent professional advice before acting upon the information contained herein.